It is that time of year again—when employees are going through open enrollment. Usually, employees stay with their prior year’s election, whether it’s the amount they defer into a corporate 401(k) or the type of health plan coverage. In other words, the status quo wins out most of the time.
Inertia is a big issue when it comes to annual workplace benefit considerations. Employees should spend more time educating themselves about their various options. One example is the decision of whether to enroll in a qualified high deductible health plan (HDHP) that includes a health savings account (HSA).
A HDHP accompanied by a HSA can be a very powerful way to bolster your retirement readiness profile. Most employees are unaware that HSA funds can be invested, and the invested portion can be seen as a specialized retirement account for health care.
It’s important to note that HSAs are much different than flexible spending accounts (FSAs). Unlike a FSA, a HSA is owned by the employee and is portable. If you leave your employer, you can take your HSA with you. And HSA funds do not need to be spent down each year like FSA funds. In fact, the objective should be to grow your HSA over time.
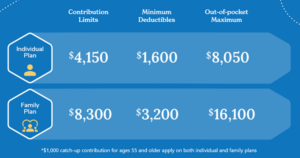
2024 HSA and HDHP Numbers
Not all employers offer a HDHP. If your employer does, you should analyze whether the HDHP is a viable option for you and your family. Here are some things to keep in mind when you are making your health plan benefit election:
- Start with looking at the premiums for each offered plan. But don’t forget that health insurance premiums paid by an employee are tax deductible, which translates to a lower after-tax cost. For example, a $500/month premium for a taxpayer in the 24% federal tax bracket is effectively only $380/month.
- Factor in the tax benefit of making HSA contributions. For an individual, the 2024 maximum contribution to a HSA is $4,150. For a family plan, it is $8,300. If you’re 55 or older, you can contribute an extra $1,000 per person over 55. These contributions are tax deductible and can be a significant factor in the analysis. A contribution of $8,300 for a household in the 24% federal tax bracket equals $1,992 in federal taxes.
- Look for employer contributions to your HSA. These contributions count against the total you can contribute to your HSA and are not tax deductible, but they help offset the deductible on a HDHP and are not taxable to you.
- Try to predict what you think your medical expenses will be for next year by looking at your past year’s medical usage.
- Be sure to understand the out-of-pocket maximum costs across all plans. You’ll need to understand how the deductible, co-pays, coinsurance and out-of-pocket maximum will work for each plan.
A HDHP is not ideal for everyone, particularly those who know they will be facing high medical costs in the future (e.g., undergoing an operation, giving birth, having a preexisting condition). The ideal candidate for a HDHP is a person or household that is generally healthy and does not experience a high level of predictable out-of-pocket health care costs.
Final thoughts
We wrote a very in-depth article about the benefits of a HSA this past summer. Suffice it to say that the HSA tax benefits are the most generous of any retirement savings vehicle legislated by Congress. The tax advantages offered by a HSA can have a significant positive impact on your long-term financial picture. If you are interested in discussing your health insurance options during open enrollment or leveraging the power of a HSA, please reach out to our team.
Disclaimer:
The information provided is for educational and informational purposes only and does not constitute investment advice and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor’s particular investment objectives, strategies, tax status or investment horizon. The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward-looking statements. Please note that any such statements are not guarantees of any future performance and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
All information has been obtained from sources believed to be reliable, but its accuracy is not guaranteed. There is no representation or warranty as to the current accuracy, reliability or completeness of, nor liability for, decisions based on such information and it should not be relied on as such.
Milestone Financial Planning, LLC (“Milestone”) is a fee-only financial planning firm and registered investment advisor headquartered in Bedford, NH. Registration does not imply a certain level of skill or training. Milestone works with clients on an ongoing, long-term basis, providing financial planning, tax planning, retirement planning, and investment management services. Fees are based on assets under management and may include a financial planning fee. Milestone receives no commissions or referral fees and, as a fiduciary, is required to act in clients’ best interests. Advisory services are offered only where Milestone and its representatives are properly licensed or exempt from licensure. More information, including fees and principal risks, is available in Milestone’s Form ADV Part 2A. For help with your investments or financial planning, contact one of our fee-only advisors.